You may have seen a little percentage known as the cost ratio if you invest in mutual funds. Even while it might not seem like much—perhaps 0.5%, 1%, 1.5%, or more—it might have an effect on your investment results over a number of years.
So, what is expense ratio in mutual funds, And why should investors be aware of it?
The expense ratio, to put it simply, shows how much it costs to run and manage a mutual fund scheme. Investment management, administration, registrar services, custody, distribution-related fees, and other authorized expenditures are examples of these costs. The NAV of the fund reflects the cost, which is stated as a proportion of the scheme’s assets.
The crucial thing to remember is that you often don’t get a separate charge for the expenditure ratio. Rather, the NAV and, eventually, the return to investors are impacted by allowable expenditures that are charged to the plan.
This guide goes over how expense ratios operate, what makes up a healthy expense ratio, why direct plans often have lower costs than regular plans, and how beginners may use this information to compare mutual funds.
READ MORE: https://marketmantra2026.in/5-star-mutual-funds-in-india-2026/ https://x.com/Mf360WW/status/2102641845880938527?s=20
What Is Expense Ratio in Mutual Funds?
So, what is expense ratio in mutual funds in practical terms?
The yearly amount of a mutual fund’s assets used to pay approved operating and management costs is known as the expense ratio, sometimes known as the Total Expense Ratio (TER).
Assume, for instance, that the cost ratio of a mutual fund is 1%.
This does not imply that you will be required to pay 1% of your investment annually.
Rather, the cost is applied to the assets of the scheme and included in the NAV computation of the fund.
According to AMFI, the daily NAV reported to investors is after subtracting relevant expenditures, whereas TER is computed as a percentage of the scheme’s average NAV.
Simple example
Let’s say you have ₹1,00,000 invested in a mutual fund with a 1% applicable cost ratio.
A simplified example would be:
₹1,00,000 × 1% = ₹1,000 per year
This is only an example; the real cost impact is dependent upon the daily assets of the plan and the changing value of your investment.
The amount that is taken out of your bank account is not always ₹1,000.
Rather, the NAV is affected by the scheme’s costs, which lower the assets available to participants.
Why Do Mutual Funds Charge an Expense Ratio?
A mutual fund is not free to operate.
There are several activities involved in running a scheme.
For example, a fund may need to pay for:
- Investment management
- Research and analysis
- Fund administration
- Custody services
- Registrar and transfer-agent services
- Audit expenses
- Investor communication
- Permitted marketing and distribution expenses
- Certain transaction-related costs
- Other regulatory and operating expenses
Among the costs related to managing mutual fund schemes include investment management, administration, marketing, transaction charges, registrar fees, custodian fees, and audit fees, according to AMFI.
In essence, the expenditure ratio permits these allowed expenses to be recouped from the plan within a particular regulatory framework.
How Does Expense Ratio Affect Mutual Fund Returns?
For long-term investors, this is where the subject becomes most crucial.
Assume that the gross investment performance of two comparable funds is equal before expenditures.
All other things being equal, Fund A has a cost advantage if its costs are lower than those of Fund B.
The change may appear insignificant in the near term.
However, when investment returns compound over a period of ten, fifteen, or twenty years, the effect may become increasingly significant.
Imagine, for instance, that two investments, each beginning with ₹5 lakh, provide the same gross return before expenditures.
Over time, the disparity may compound if one investment continually loses slightly more due to expenditures each year.
For this reason, investors shouldn’t discount a little proportion just because it doesn’t seem like much.
TER directly affects a scheme’s NAV, according to AMFI, and, all other things being equal, fewer expenses can lead to a better NAV.
What Is a FAIR Expense Ratio for Mutual Funds?
For every mutual fund, there isn’t a particular expense ratio that is fundamentally good or poor.
The proper comparison is dependent upon:
- Fund category
- Active or passive strategy
- Direct or regular plan
- Fund size
- Investment approach
- Level of portfolio management
- Comparable funds
For example, the cost ratios of an actively managed small-cap fund and an index fund shouldn’t always be the same.
An actively managed fund could need a lot more research and portfolio management work than an index fund, which sticks to a benchmark with very less active securities selection.
Because their portfolios aim to monitor an index rather than actively choose stocks, passive funds like index funds and exchange-traded funds (ETFs) often have lower fee ratios, according to AMFI.
Therefore, compare an expenditure ratio with similar funds rather than just asking if it is “low.”
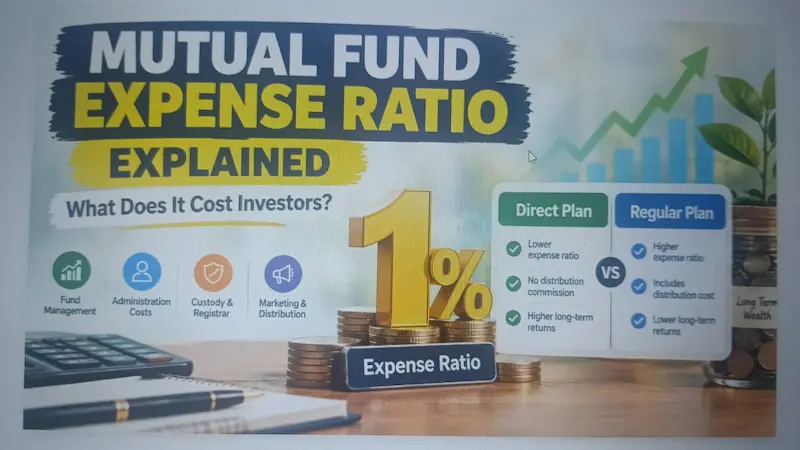
Direct Plan vs Regular Plan Expense Ratio
The difference between direct and regular planning is one of the most crucial concepts for beginners to grasp.
The underlying portfolio and fund management are often the same for both plans, which are part of the same mutual fund scheme.
Distribution is the main distinction.
A direct plan is bought straight from the mutual fund without passing the investment via a distributor, while a conventional plan requires a distributor.
Direct plans often have a lower expenditure ratio since distributor commissions are not included in the same manner.
The same scheme’s direct and regular plans have the same portfolio and fund manager, but their expense ratios differ, with direct plans often having lower costs, according to AMFI.
Example
Suppose a hypothetical scheme has:
Direct Plan: 0.60% expense ratio
Regular Plan: 1.10% expense ratio
The difference is:
0.50 percentage points
That change might not seem like much.
However, recurrent expenses can have a big impact when investments are held for a long time since the money that would have stayed invested could have earned returns on its own.
For this reason, long-term investors tend to maintain a careful eye on direct-plan expenses.
Is a Lower Expense Ratio Always Better?
Not always.
This is a crucial distinction.
From a financial standpoint, a lower expense ratio is advantageous, but it shouldn’t be the only factor to consider when choosing a mutual fund.
Consider two funds that are actively managed.
Fund A levies a 0.70% fee.
Fund B levies a 1.10% fee.
The less expensive fund could have an advantage if both have comparable performance and the same investing methods.
Let’s say, however, that Fund B has continuously outperformed its category and benchmark in terms of risk-adjusted performance after expenditures.
The larger picture would be overlooked if Fund A were just selected due to its lower expenditure ratio.
When assessing a fund, AMFI’s investor guideline advises considering TER in addition to benchmark performance, risk, and past returns.
Thus, the objective ought to be:
Reasonable cost + suitable strategy + appropriate risk + consistent performance
What Is the Difference Between TER and Expense Ratio?
The expense ratio and Total Expense Ratio (TER) are used by the majority of retail investors to sum up the total yearly operational costs associated with a mutual fund scheme.
The official regulatory word that investors frequently come across in fund filings is TER.
According to AMFI, TER is a percentage of the scheme’s average NAV that represents all allowed expenditures.
Therefore, you are effectively looking at the fund’s total cost ratio when you see a “TER” on a mutual fund website.
Are Expense Ratios Deducted Monthly?
Sometimes investors believe that the cost ratio is taken out of their bank account on a monthly basis by a fund provider.
It doesn’t operate that way.
The NAV estimates for the program take mutual fund expenses into account.
Once the relevant costs have been subtracted, the NAV is shown.
According to AMFI, the daily NAV is revealed after expenditures are subtracted, and the TER is determined using the scheme’s average NAV.
As a result, the term “mutual fund expense ratio” will typically not appear as a distinct item on your bank account.
The fund structure incorporates the expense.
Does Expense Ratio Reduce Your SIP Returns?
Indeed, SIP investors may also be harmed by expenditures.
Consider making a ₹5,000 monthly investment for 15 years.
Over time, each SIP installment has the potential to compound.
The amount left over for investors after expenses is reduced if the fund has greater ongoing costs.
When comparing funds that are generally identical, the distinction becomes quite significant.
Investors should refrain from computing the expense ratio as though the same percentage were simply subtracted once a year from the whole SIP amount. The scheme’s daily assets and NAV are the real mechanics.
Because the expense ratio is a fund-level expenditure rather than a traditional yearly bill delivered to each investor, this distinction is crucial for educating novices about mutual funds.
How to Check the Expense Ratio of a Mutual Fund
Checking a mutual fund’s expense ratio is relatively straightforward.
You can generally find the current TER through:
- The mutual fund AMC’s website
- AMFI’s TER disclosure
- Scheme documents
- Fund factsheets
- Investment platforms
Investors can look at expense-ratio statistics for mutual fund schemes through AMFI’s dedicated TER database.
Checking the current TER is preferable than depending on an outdated article, screenshot, or social media post because costs are subject to change.
Mutual funds must provide TER information, according to AMFI, which also offers daily TER information via its portal.
What Is the Maximum Expense Ratio Allowed in India?
The costs that mutual fund schemes can charge are limited by India’s rules and regulations.
Investors should exercise caution when reading outdated publications, though, as language and regulations are subject to change.
The Base Expense Ratio (BER) structure used in SEBI’s 2026 mutual-fund framework has varying restrictions based on the scheme’s assets and relevant category. The regulations approach various brokerage, transaction expenses, and statutory taxes differently.
For instance, instead of using a single, universal percentage for all mutual funds, a 2026 SEBI document displays a base-expense structure that varies by asset slab.
As a result, investors shouldn’t depend on generalizations like “all mutual funds can charge up to X%.”
The relevant regulatory provisions for the scheme determine the applicable limit.
Does a Large Mutual Fund Have a Lower Expense Ratio?
It is able to.
Since asset-size slabs are typically used in the regulatory expense structure, the allowable base expense ratio may decrease as assets rise.
This illustrates how bigger schemes might distribute some operational expenses over a wider range of assets.
Different base-expense limitations are provided for each asset slab under SEBI’s 2026 framework.
However, a huge fund does not always have the lowest ratio of expenses.
It is usually advisable to verify the real TER charged for the particular program and plan.
Expense Ratio for Index Funds
Instead than significantly depending on active stock selection, index funds are made to track a certain market index.
Index funds often have lower operational expenses than many actively managed funds since the investing strategy is typically more rules-based.
In particular, AMFI points out that reduced expense ratios are a feature of passive products like index funds and exchange-traded funds (ETFs).
Investors should examine more than simply the expenditure ratio, though.
For an index fund, take into account:
- Tracking difference
- Tracking error
- Fund size
- Liquidity
- Benchmark
- Portfolio replication method
- Fund-house operations
If it properly follows its benchmark, a fund with a little higher cost ratio could still produce competitive outcomes.
Expense Ratio for Active Mutual Funds
Fund managers of active mutual funds base their investing choices on the stated strategy of the scheme.
The process of managing funds may include:
- Company research
- Sector analysis
- Portfolio construction
- Risk management
- Buying and selling securities
- Monitoring companies
- Rebalancing
As a result, active funds may incur more costs than passive funds.
However, greater management does not always follow from more spending.
Whether the fund’s approach and performance warrant the extra expense is the crucial question.
Since the NAV and stated returns already account for the relevant scheme expenditures, investors should look at performance after expenses.
Expense Ratio and Mutual Fund NAV
It is important to know how the spending ratio and NAV are related.
Let’s say a fund has ₹1,000 crore worth of stocks and other securities.
Additionally, there are some approved costs for the fund.
These costs are applied to the assets of the program.
Consequently, the impact of such costs is reflected in the NAV that investors observe.
AMFI makes it clear that TER directly affects NAV and that daily NAV is revealed after expenditures are subtracted.
Because of this, investors typically do not view the expenditure ratio as a distinct transaction.
The NAV of the fund already takes it into account.
Does Expense Ratio Matter More for Long-Term Investors?
As the investment time gets longer, it may become more important.
Think about two investors who put in ₹2 lakh apiece.
Investment returns compound on the remaining amount invested, so if one fund often costs a little bit more each year, the difference may pile up.
This is particularly important for investors who want to achieve long-term objectives like:
- Retirement
- Children’s education
- Long-term wealth creation
- Financial independence
Ongoing expenses may grow more important the longer the money is invested.
This does not mean that investors should become fixated on minute variations across funds.
This means that when two otherwise similar assets have significantly differing expense ratios, expenses should be taken into consideration.
How Much Expense Ratio Is Too High?
A mutual fund’s cost is not always calculated using the same percentage.
Rather, inquire:
“When compared to similar funds that offer a similar strategy, is this expense ratio reasonable?”
For instance, because the fundamental investing strategies of an index fund and an actively managed small-cap fund differ, comparing their TERs may not reveal anything.
A more accurate analogy would be:
Active small-cap fund vs other active small-cap funds
or
Nifty 50 index fund vs other Nifty 50 index funds
This creates a more meaningful cost comparison.
Common Mistakes Investors Make With Expense Ratio
Mistake 1: Ignoring it completely
Some investors select funds entirely based on past returns and never check the costs.
Mistake 2: Choosing only the cheapest fund
Low cost is useful, but the cheapest fund is not automatically the most suitable investment.
Mistake 3: Comparing different categories
An index fund and an actively managed thematic fund should not necessarily have the same cost structure.
Mistake 4: Confusing expense ratio with exit load
These are different costs.
Expense ratio relates to the ongoing operation of the scheme.
Exit load is a charge that may apply when units are redeemed under specified conditions.
Mistake 5: Looking at outdated TER information
Expense ratios can change, so always check current disclosures.
Mistake 6: Forgetting the direct-versus-regular difference
For long-term investors, the difference between direct and regular plan expenses can become meaningful.
Expense Ratio vs Exit Load
These two terms are often confused.
| Feature | Expense Ratio | Exit Load |
|---|---|---|
| Purpose | Covers permitted scheme expenses | Discourages/charges certain early redemptions |
| Frequency | Ongoing | Usually applies when redeeming under specified conditions |
| Deducted from | Scheme assets/NAV | Redemption proceeds, where applicable |
| Applies automatically? | Reflected in NAV | Only when applicable |
| Main concern | Ongoing investment cost | Early withdrawal cost |
Understanding this difference can make it easier to evaluate the actual cost of a mutual fund investment.
Does a Higher Expense Ratio Mean Higher Returns?
No.
A fund with a higher cost ratio is not required to provide better returns.
A costly fund may perform poorly.
A less expensive fund could perform better.
The expenditure ratio is not a performance guaranty; it is a cost.
Because of this, investors should consider risk and benchmark performance in addition to a fund’s returns after fees.
Rather than using cost ratio as the only selection criterion, AMFI’s investor guideline expressly advises looking at TER in conjunction with other considerations including risk and performance.
How Beginners Should Evaluate Expense Ratio
If you are new to mutual funds, you don’t need a complicated formula.
Use this simple checklist:
Step 1: Identify the fund category
Is it large-cap, flexi-cap, mid-cap, small-cap, hybrid, debt or an index fund?
Step 2: Check the plan
Determine whether you are looking at a direct or regular plan.
Step 3: Check the current TER
Use the AMC or AMFI rather than relying on outdated third-party information.
Step 4: Compare similar funds
Look at funds with comparable investment strategies.
Step 5: Check performance after expenses
Don’t judge a fund only by its cost.
Step 6: Examine risk
A lower expense ratio cannot compensate for taking inappropriate investment risk.
Step 7: Consider your time horizon
When money is invested for several years, recurring fees become more serious.
This simple technique can help you comprehend mutual fund cost ratios without getting bogged down in complex language.y.
The Bigger Lesson About Mutual Fund Costs
Expense ratio is only one part of the cost structure of investing.
Investors should also understand:
- Exit load
- Taxes
- Transaction charges where applicable
- Brokerage and transaction-related costs
- Tracking difference for passive funds
- Direct versus regular plan costs
The secret is to avoid looking for a fund with the lowest figure at all costs.
Instead, choose a fund that makes sense in terms of total cost, strategy, risk, and expected function in your portfolio.
It’s possible that two whole distinct investing strategies won’t be decided by a 0.20% difference.
However, the cost difference should be taken into consideration if two funds are quite similar and one regularly costs less.
Final Thoughts
One of the key skills that any mutual fund investor should acquire is an understanding of the cost ratio in mutual funds.
The continuous cost of running and overseeing a mutual fund scheme is represented by the expense ratio. Instead of showing up as a separate charge to investors, it is often represented through the scheme’s NAV.
Because regular expenditures take up less of the scheme’s assets, a lower expense ratio might be advantageous, particularly over extended periods.
However, choosing a mutual fund should never be based solely on price.
Comparing funds in the same category, knowing if you are investing in a direct or regular plan, looking at long-term performance, taking risk into account, and checking the current TER are all superior strategies.
The easiest guideline for beginners is:
Avoid looking for the lowest ratio of expenses. Recognize the price, compare it against similar funds, and confirm that the fund itself aligns with your investing objectives.
You have a far better basis for mutual fund investment when you combine cost awareness with prudent diversification, effective risk management, and a long-term strategy..
Frequently Asked Questions
In simple terms, what is the expense ratio in mutual funds?
It is the portion of a mutual fund’s assets utilized to pay authorized costs associated with running and overseeing the scheme.
Is a mutual fund’s 1% fee ratio excessive?
The plan and fund category will determine this. Instead of evaluating a 1% expense ratio in itself, it should be compared to similar funds.
Does the expenditure ratio lower the returns on mutual funds?
Indeed. Permitted expenditures have an impact on the NAV and, consequently, the returns that investors get since they are charged to the plan.
Does a lower expense ratio make direct mutual funds superior?
Because conventional plans’ commissions and delivery costs are not included in the same manner, direct plans often have lower expense ratios. Whether you require marketing or advisory help will also determine whether a direct approach is suitable.
Disclaimer: This article is for educational purposes only and is not personalised investment advice. Mutual fund investments are subject to market risks. Investors should read the relevant scheme documents and check current official disclosures before investing.